
This profile is also available in French
Biography
Why tax expenditure reporting is a missing link in financing for development
FfD4 Countdown: A Watered-Down Proposal on Tax Expenditures Risks Undermining Countries’ Domestic Revenue Mobilisation
Governments’ decisions to grant preferential tax treatments have a direct impact on their ability–or inability–to finance their sustainable development goals….
What should a ‘new deal’ on international tax look like for developing countries?
The OECD secretariat recently proposed a “stock taking exercise” to “re-examine how international tax rules currently meet the needs of…
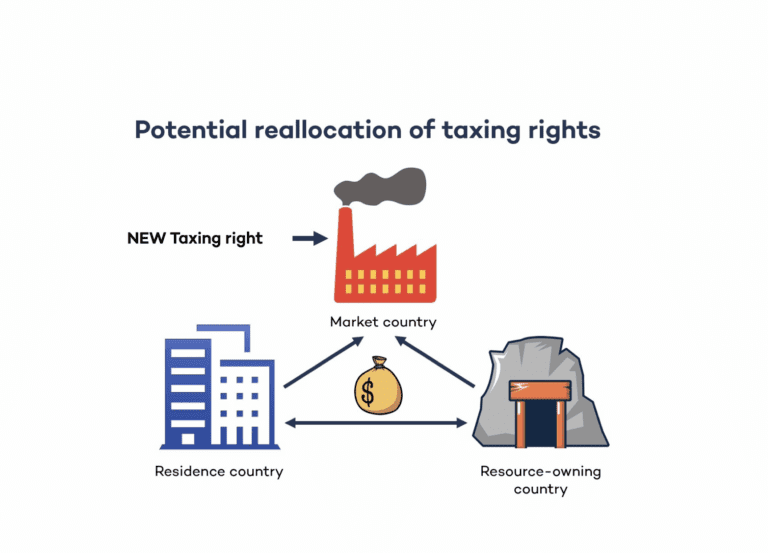
Resource-Rich Countries and the Digital Tax Agenda
Those of us involved in the mining sector could be forgiven for thinking that the OECD’s program of work on…
A withhold up in Mongolia? Thoughts on the renewed tax debate around Oyu Tolgoi
This piece is available in Mongolian here. Governments of mining countries are vulnerable to investors using double tax agreements (DTAs)…
New Toolkit Aims to Curb Transfer Mispricing in African Mining
Recently, 38 African tax authorities convened in Abuja for the International Conference on Tax in Africa, organised by the African…
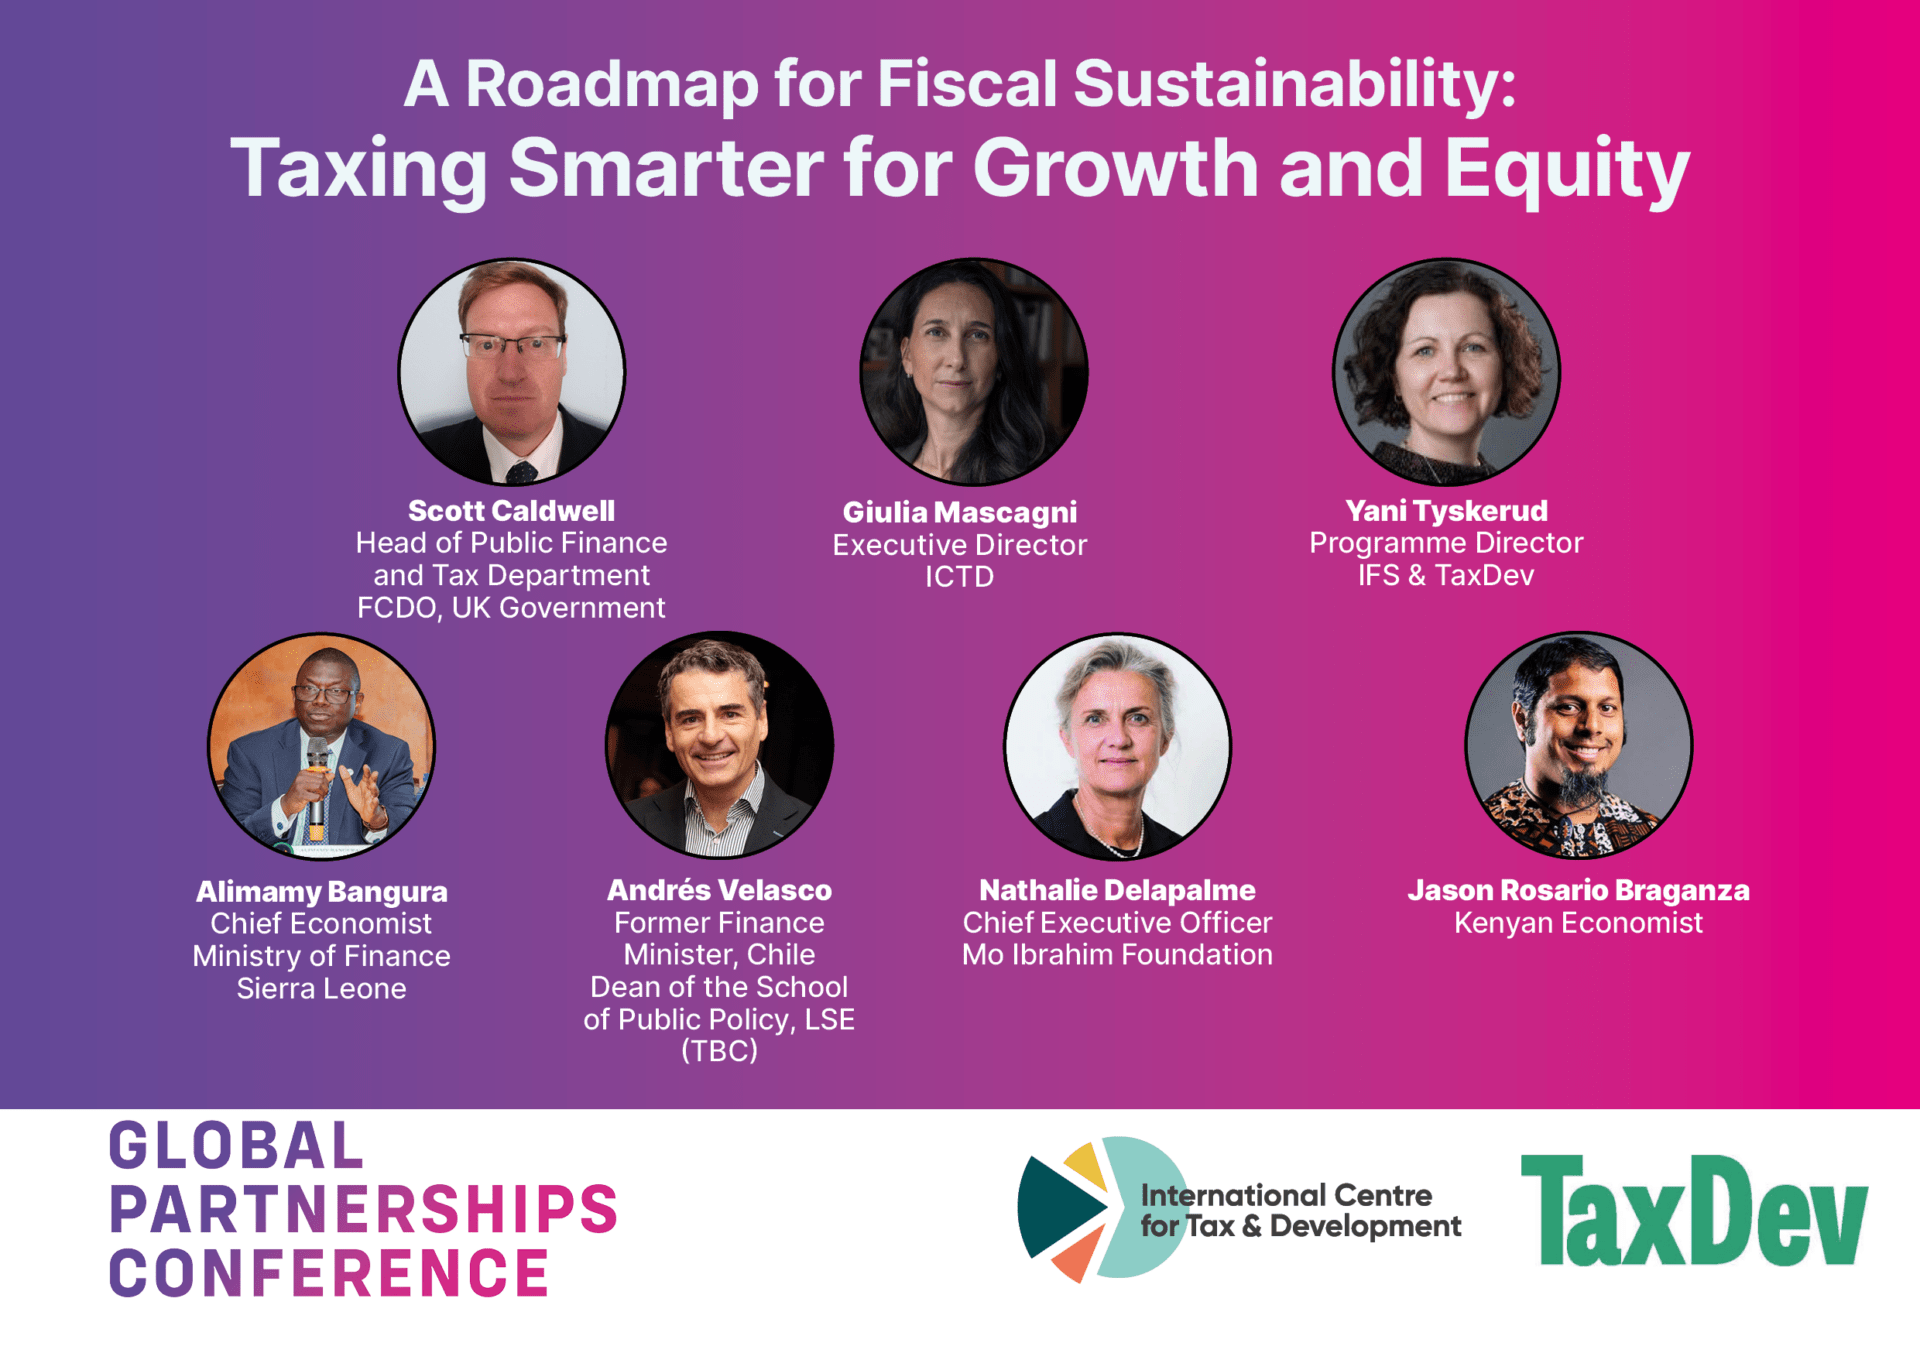
Fiscal sustainability through partnerships and evidence: insights from the Global Partnerships Conference
In person
•
Timezone: Bangkok time, GMT+7
Tax expenditures, including exemptions, deductions, credits and reduced rates, are among the most widely used tax policy tools, yet they are often costly, poorly governed and subject to limited scrutiny. Revenue foregone through tax expenditures worldwide amounts to around USD
Virtual
•
Timezone: Europe/London
