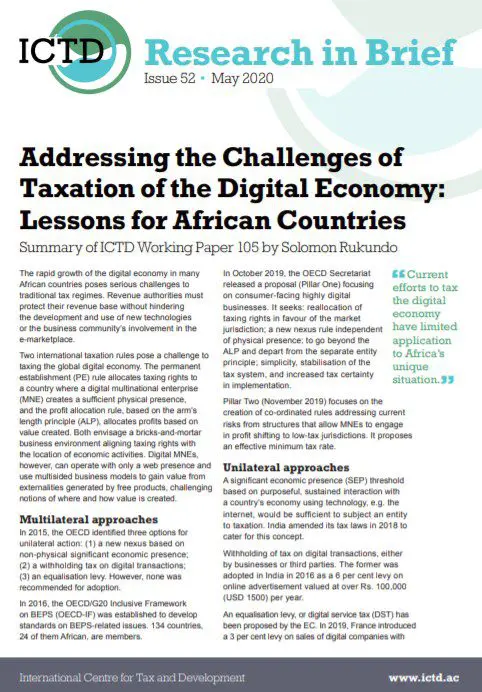
The rapid growth of the digital economy in many African countries poses serious challenges to traditional tax regimes. Revenue authorities must protect their revenue base without hindering the development and use of new technologies or the business community’s involvement in the e-marketplace. Two international taxation rules pose a challenge to taxing the global digital economy. The permanent establishment (PE) rule allocates taxing rights to a country where a digital multinational enterprise (MNE) creates a sufficient physical presence, and the profit allocation rule, based on the arm’s length principle (ALP), allocates profits based on value created. Both envisage a bricks-and-mortar business environment aligning taxing rights with the location of economic activities. Digital MNEs, however, can operate with only a web presence and use multisided business models to gain value from externalities generated by free products, challenging notions of where and how value is created.