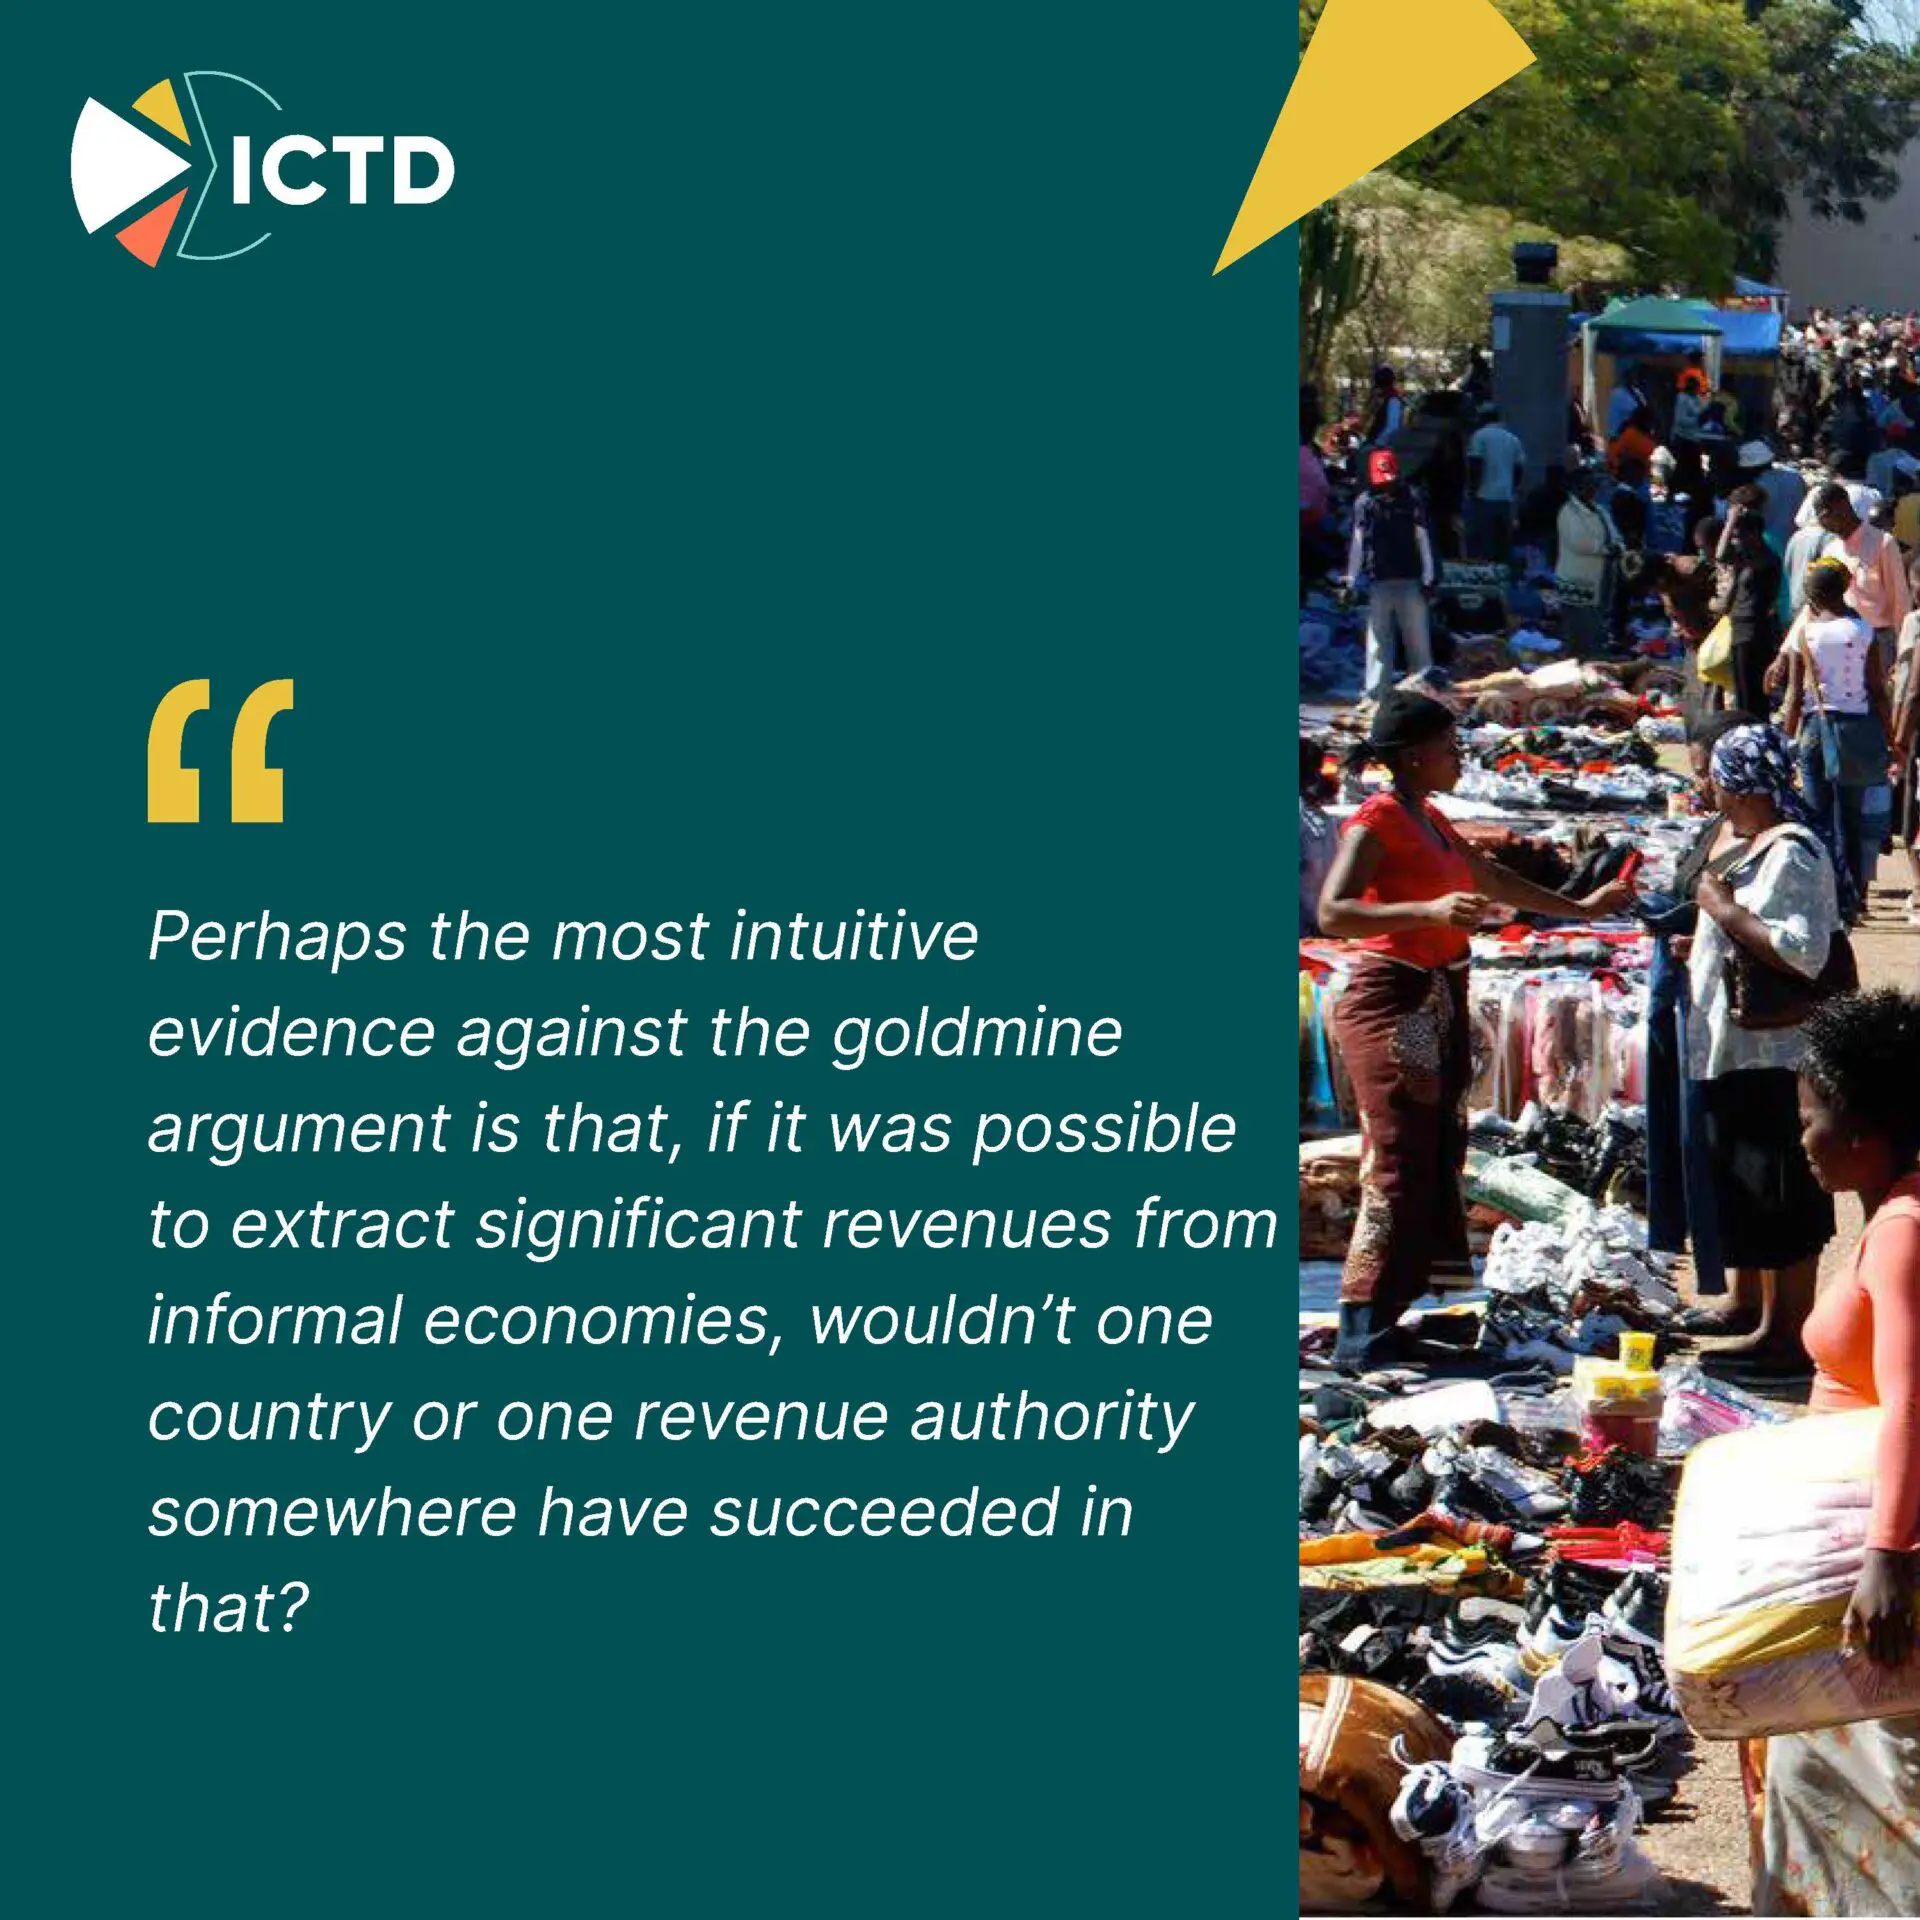
The promise of untapped revenue is a much-repeated argument for more aggressive and broader taxation of informal economies. Referencing the large size of informal sectors and uncaptured income, as well as limited revenues generated from informal sector specific tax handles, the argument suggests that informality represents a ‘goldmine’ of untaxed revenue. This policy brief reviews why the ‘goldmine argument’ is false. While it may sound intuitively correct, it is based on a common misunderstanding of the underlying statistics, tax handles, and income distributions within informal sectors. Doubling down on current approaches to taxing informal economies is in fact unlikely to produce substantial revenue gains, while raising collection costs and equity concerns – largely because current approaches are not targeted at capturing higher-income operators in informal sectors. Consequently, a more productive approach for revenue authorities to engage with informal sectors should rest on four pillars: targeting, development, data and dialogue.
Key messages
- A common argument for taxing informal economies more aggressively and broadly proposes that because of their size, contribution to GDP and limited tax payments, they represent a potential tax ‘goldmine’. This argument is misleading and based on a misunderstanding of the underlying data, income structures and tax handles.
- While informal economies make up a large part of the labour force in lower-income countries, statistics about their contributions to GDP are less reliable. Incomes in informal economies are also highly unequal. While taxable incomes exist, they are concentrated among a few specific sub-sectors, actors and activities.
- Most current taxes aimed at informal sectors are broad-based and poorly equipped to target these higher incomes. This has led to limited revenues, high collection costs and negative equity implications. Doubling down on them is not a promising strategy for revenue generation.
- A better strategy for revenue generation relies on taxes which are specifically targeted at higher-income earners and untaxed wealth, a more developmental approach to engaging with informal sectors, better data collection and dialogue with informal actors. Some of the most promising tax strategies here are not aimed at informality itself, but at increasing lower-income countries’ (LICs) capacity to identify and tax higher incomes and wealth irrespective of the sector.