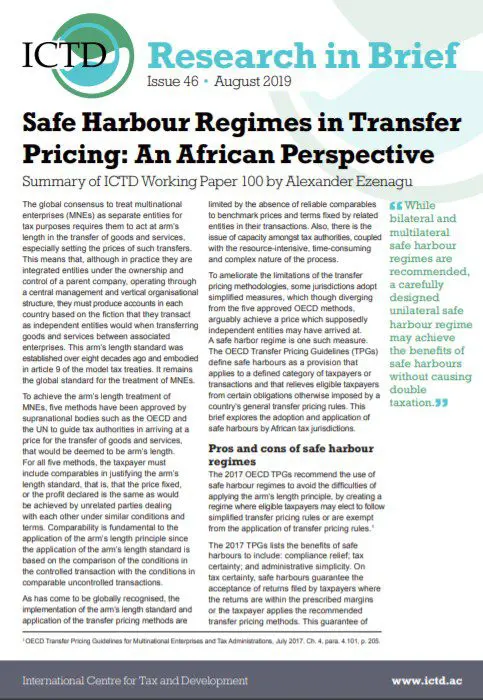
The global consensus to treat multinational enterprises (MNEs) as separate entities for tax purposes requires them to act at arm’s length in the transfer of goods and services, especially setting the prices of such transfers. This means that, although in practice they are integrated entities under the ownership and control of a parent company, operating through a central management and vertical organisational structure, they must produce accounts in each country based on the fiction that they transact as independent entities would when transferring goods and services between associated enterprises. This arm’s length standard was established over eight decades ago and embodied in article 9 of the model tax treaties. It remains the global standard for the treatment of MNEs. This ICTD Research in Brief is a two-page summary of ICTD Working Paper 100 by Alexander Ezenagu.