About
The pillars of our work
Rigorous, collaborative research
Purposeful communication and policy engagement
Applied research training and mentoring
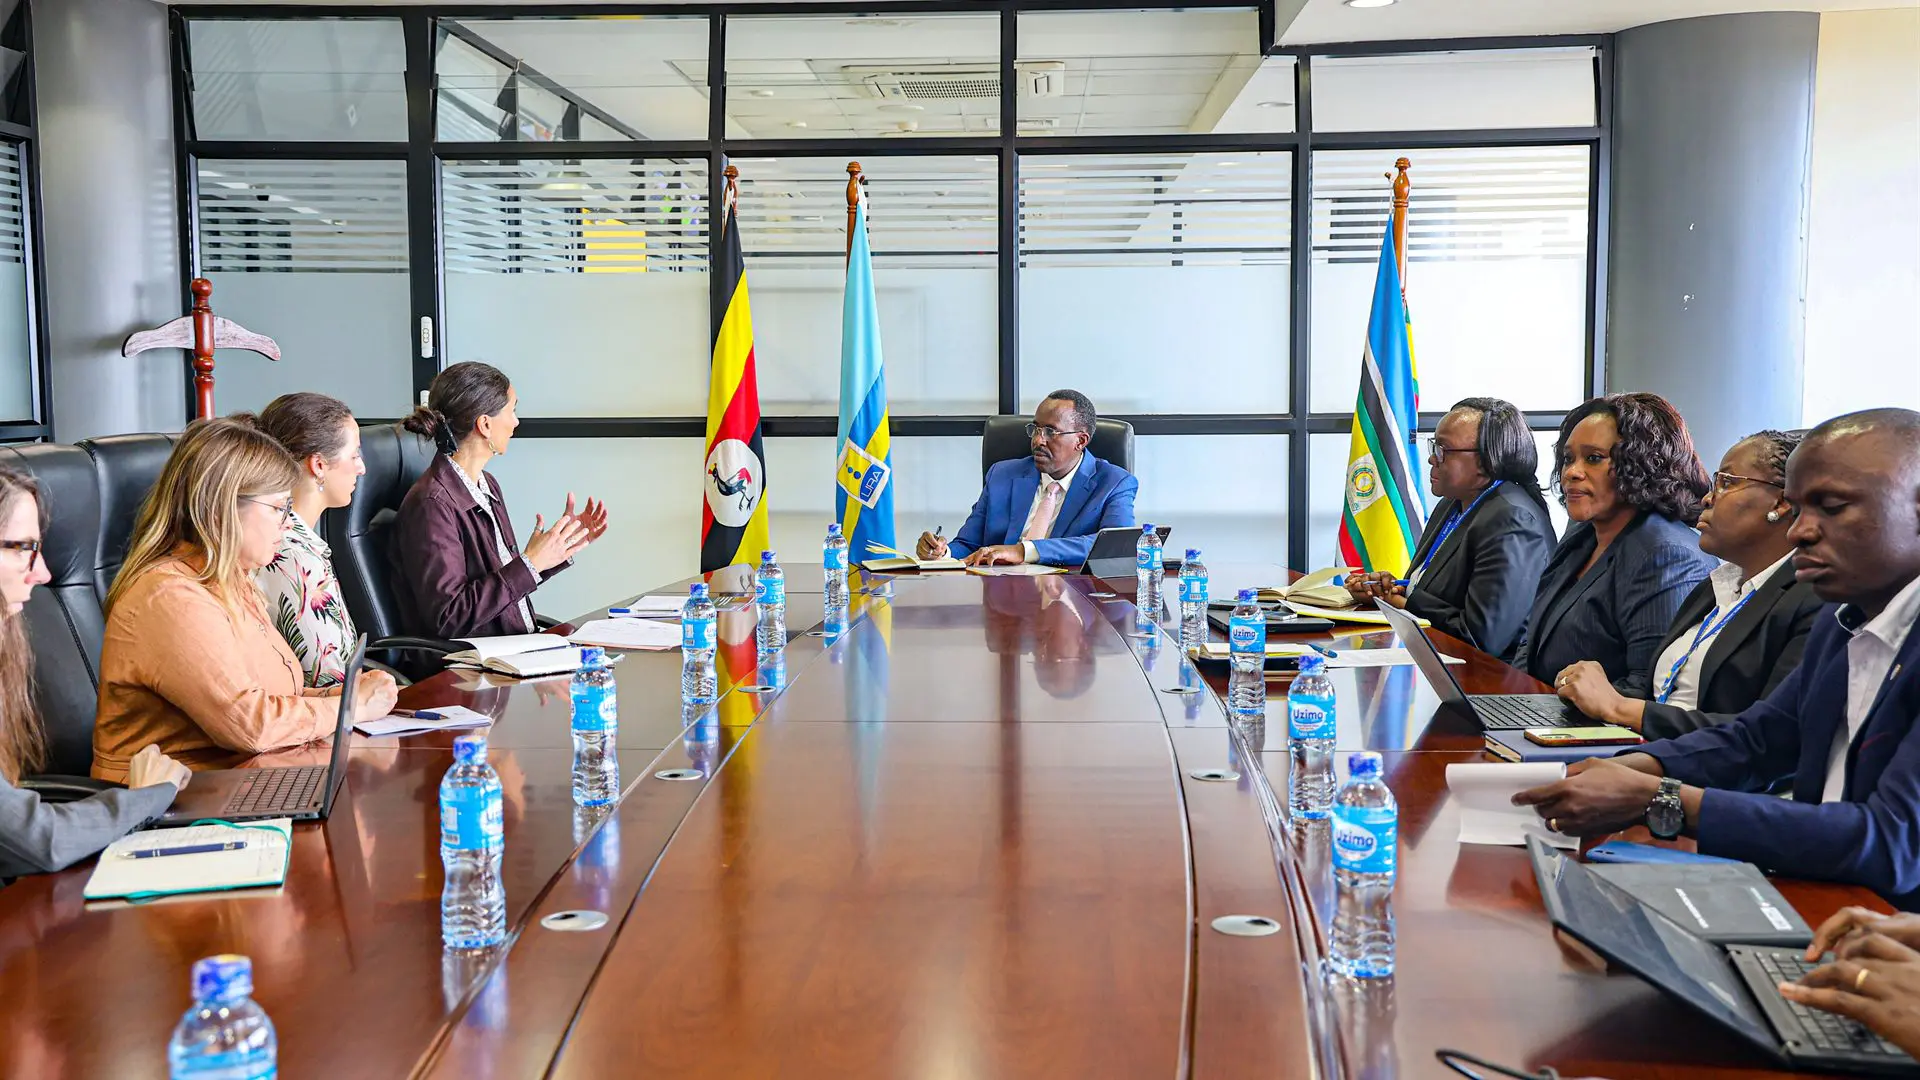
Our Impact
Our Home Institution
Funders
Gates Foundation
The Gates Foundation is a philanthropic organization that works to dramatically reduce disease and poverty and build a more equal world. Its charitable support focuses on innovative products, ideas, and approaches that have the potential to save and improve the greatest number of lives.
Norwegian Agency for Development Cooperation (Norad)
The Norwegian Agency for Development Cooperation (Norad) is responsible for managing large parts of Norway’s development assistance to other countries. The agency manages funding, provide expert advice and monitor results to help ensure that Norwegian development policy makes a real difference for people, the environment and the climate.
UK Government, FCDO, Global Research and Technology Development
Global Research and Technology Development (GRTD) is the UK government’s flagship research and innovation portfolio for international development. Funded by the Foreign, Commonwealth & Development Office (FCDO), GRTD brings together science, partnerships and innovation to build prosperity, resilience and security around the world – supporting a world free from poverty on a liveable and safer planet.



Principles of Engagement with Partners
Collaborative research and engagement are central to ICTD’s work. We work closely with a wide range of partners including governments, tax administrations, civil society organisations, and international agencies to produce research that is rigorous, policy-relevant, and grounded in real-world challenges.
As one of the earliest organisations to undertake sustained research partnerships with revenue authorities in Africa, we have developed a particular approach to working with tax administrations, reflecting both the opportunities and the complexities of conducting and publishing research based on administrative data.
1. Building Strong Partnerships with Tax Administrations
Strong collaboration between researchers and tax administrations can lead to better evidence, stronger policy design, and, ultimately, more equitable and effective tax systems. While researchers and practitioners have historically worked separately — often with different priorities, timelines, and expectations — partnerships between independent researchers and African revenue authorities have become more common. Over time, ICTD’s experience has shown the value of working together from the outset, and throughout research projects’ cycle.
Drawing on these experiences, ICTD and the Uganda Revenue Authority developed a set of shared principles for collaboration. These principles were later adopted by the African Tax Administration Forum (ATAF) and endorsed by UNU-WIDER. These principles remain central to ICTD’s approach to collaboration, which is outlined below.
2. Establishing a Memorandum of Understanding
Successful collaboration begins with clear expectations and open communication. Researchers and tax administrations may have different objectives, working styles, and timelines, so it is important to establish shared understandings from the start.
Partnerships are usually guided by a memorandum of understanding that clarifies:
- roles and responsibilities
- timelines and resource commitments
- processes for communication and resolving disagreements
- expectations around outputs and dissemination
Because collaborative research can require significant staff time and operational support from tax administrations, both sides should ensure that projects are realistic, well-coordinated, and aligned with institutional priorities.
3. Protecting Data and Confidentiality
Protecting taxpayer data and confidentiality is a fundamental responsibility for all parties involved in research partnerships.
Key principles include:
- administrative data shared with researchers should be anonymised before access is granted
- tax administrations retain ownership of their administrative data, while researchers can use it for agreed projects
- data should never be shared with third parties outside of agreed projects without the explicit consent of the tax administration
- arrangements around any additional data collected during research (such as survey data or interviews) should be made separately from those related to administrative data
Tax administrations are also encouraged to make aggregate revenue and performance data publicly available wherever possible, while clearly explaining methodologies, classifications, and limitations.
4. Co-Producing Research
ICTD strongly encourages research that is co-designed and co-produced with tax administration staff. Collaborative research is more likely to generate policy-relevant findings, build institutional ownership, and support uptake into practice.
Effective collaboration includes:
- using accessible, non-technical language throughout the research process
- involving tax administration staff in research design, implementation, analysis, and dissemination
- allocating dedicated personnel and sufficient institutional support for research engagement
- ensuring participating staff have the appropriate skills, experience, and time to contribute meaningfully
5. Strengthening Capacity and Sharing Knowledge
Research partnerships should create benefits for both researchers and practitioners. Beyond producing evidence, collaboration should contribute to strengthening research and analytical capacity within tax administrations.
This may include:
- training in research methods and data analysis
- practical experience in conducting and managing research projects
- support with communicating findings to policymakers and wider audiences
- joint learning throughout all stages of the research process
Practitioners are active partners in research, not simply providers of data.
6. Recognising Contributions and Intellectual Property
Collaborative research depends on contributions from many different actors, including those involved in data preparation, project coordination, implementation, analysis, and writing.
ICTD encourages:
- appropriate recognition of all substantive contributions through co-authorship or acknowledgements, in line with ICTD’s guidelines on co-authorship
- fair treatment of implementation and operational work as important research contributions
- clear agreements on intellectual property and publication rights from the outset
In general:
- tax administrations retain ownership of administrative data and internally produced institutional materials
- Researchers, identified as authors of the relevant outputs, retain authorship and intellectual ownership of their analytical outputs
- tax administrations should be able to use and disseminate research outputs with appropriate attribution and acknowledgement of authors
7. Publication, Dissemination, and Policy Uptake
Research should be communicated in ways that are accessible and useful to a wide range of audiences, including policymakers, practitioners, and the public.
Researchers working on ICTD projects are normally expected to publish the outputs of their research. More specifically, theyare encouraged to:
- publish findings in academic and policy-focused formats
- produce accessible summaries of key findings and policy implications
- disseminate outputs in relevant national or official languages where appropriate
- clearly communicate the limitations of findings and recommendations
Publications based on administrative data should only include de-identified and aggregated statistics, and should acknowledge that the views expressed are those of the authors, not necessarily those of the respective institutions.
In some cases, tax administrations may request a temporary embargo – typically no longer than 6 months – on publication where findings relate to sensitive or upcoming policy reforms.
8. Monitoring Collaboration and Impact
Both researchers and tax administrations share responsibility for ensuring that partnerships remain effective, transparent, and impactful.
This includes:
- monitoring compliance with agreed principles and highlighting any concern
- maintaining efficient communication and coordination
- tracking and communicating about how research findings influence policy and practice over time
Collaborative research works best when partnerships are based on trust, mutual respect, and a shared commitment to producing evidence that strengthens tax systems and supports public policy.
Partner Spotlight
We work with partners to generate evidence, strengthen research capacity and support reform choices grounded in real administrative, political and institutional challenges. Partner Spotlight shares recent news and updates from some of this collaborative work.
The Addis Tax Initiative (ATI) is a multi-stakeholder partnership that brings together partner countries, development partners, and supporting organisations, with an aim to foster collective action to strengthen tax systems in response to recognised gaps in development finance. ICTD and the ATI currently collaborate on several workstreams, including tax and informality, minimum standards for tax expenditure reporting, and wealth taxation.
ATAF serves as an African network that aims at improving tax systems in Africa through exchanges and knowledge dissemination. ATAF Executive Secretary, Mary Baine, is a member of ICTD’s Advisory Group; ICTD also has an MOU with ATAF working closely on several areas including informality, digitalisation and taxing high net worth individuals.
Partners