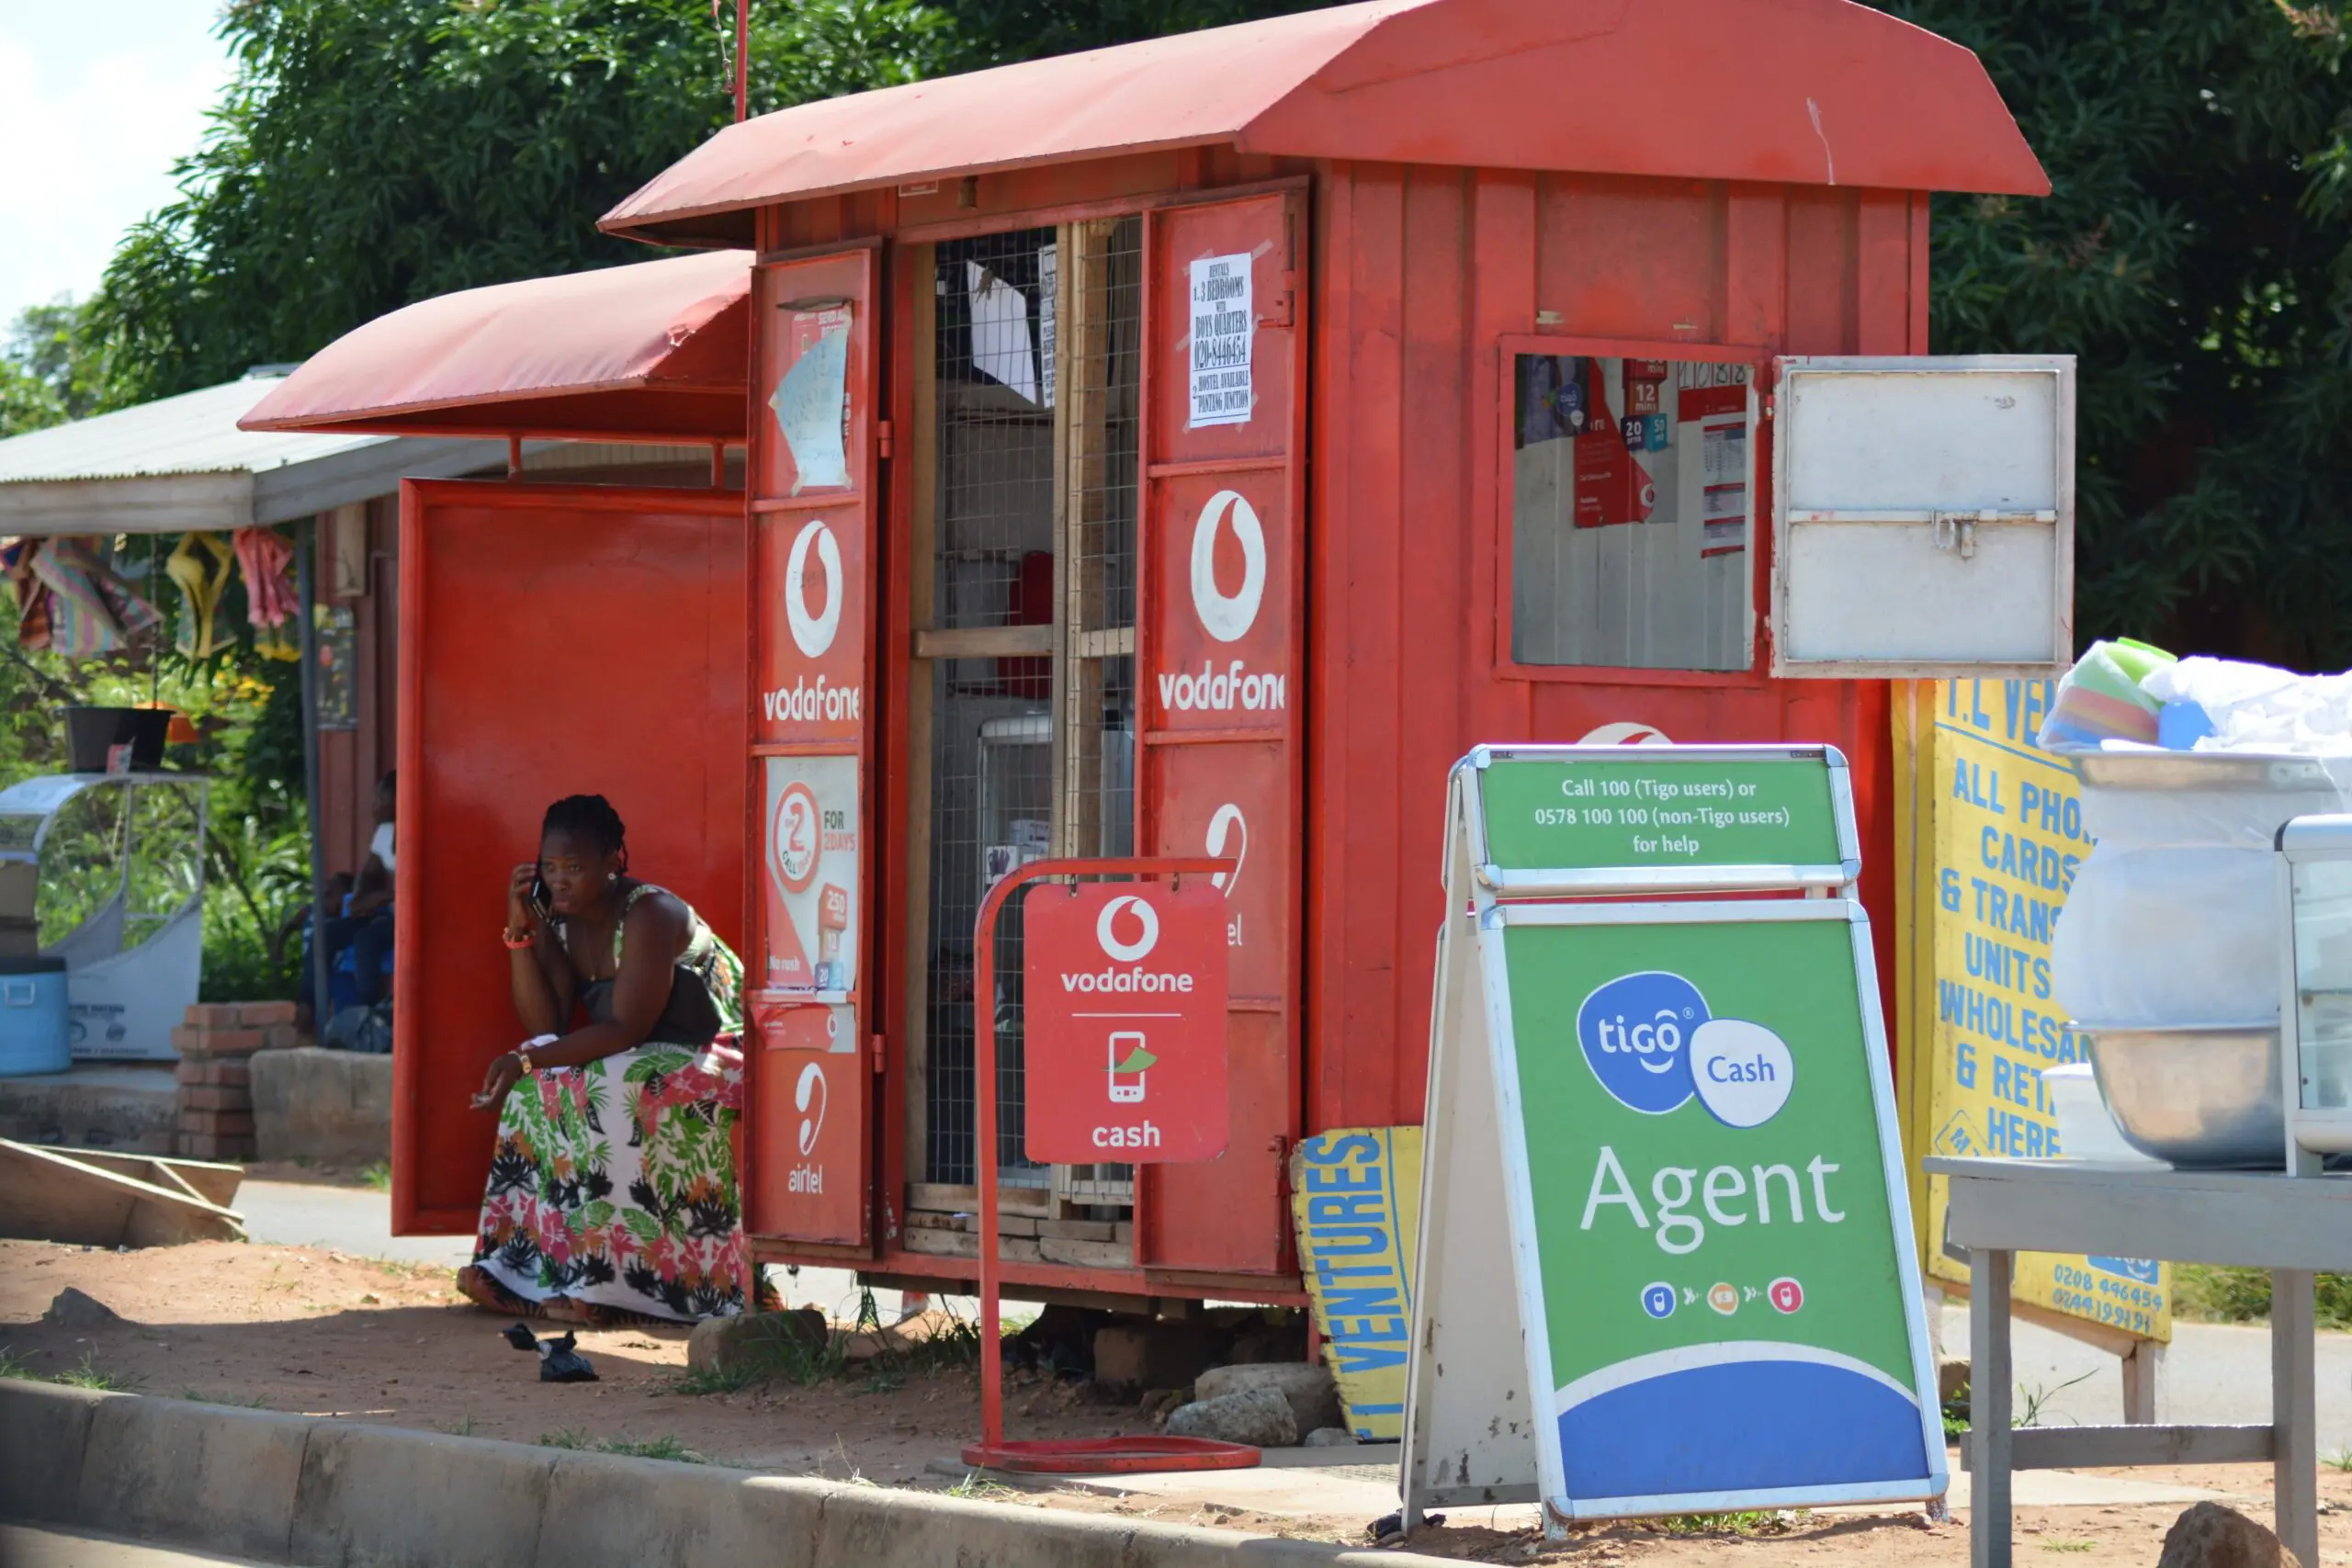
Rwanda’s two mobile operators each run their own mobile money platform: MTN MoMo and Airtel Money. For years, these were largely closed loops: moving money between them, or into a bank account, was impossible or cost extra. That friction reinforced MoMo’s market share advantage and pushed many merchants towards accepting only MoMo payments, whether via MoMoPay, MoMo’s merchant offering, or its legacy peer-to-peer (P2P) offering.
In July 2026, the National Bank of Rwanda (BNR) made eKash, the national interoperable digital payment and retail system run by RSwitch, mandatory for all off-net (cross-operator) payments up to RWF 10 million. eKash connects commercial banks, microfinance institutions and mobile money operators – such as MTN and Airtel – into a single, unified network.
Until July, a cross-operator merchant payment on eKash could incur two fees: a sending fee for the customer and a separate fee for the merchant. With a maximum capped fee of RWF 20 per P2P transfer, and cost-free merchant payments, BNR aimed to reduce transaction costs by prohibiting banks and microfinance institutions from establishing bilateral arrangements with mobile money operators. BNR Governor, Soraya Hakuziyaremye, said that “from July to September, the volume of transactions processed through eKash ha[d] increased from close 140,000 a month to 1 million.” BNR also reported 28.9 million eKash transactions in September 2026, up from 1.9 million in September 2025.
Early fieldwork suggests this is already changing how merchants get paid, how providers compete, and what the state can tax.
The economics of merchant choice
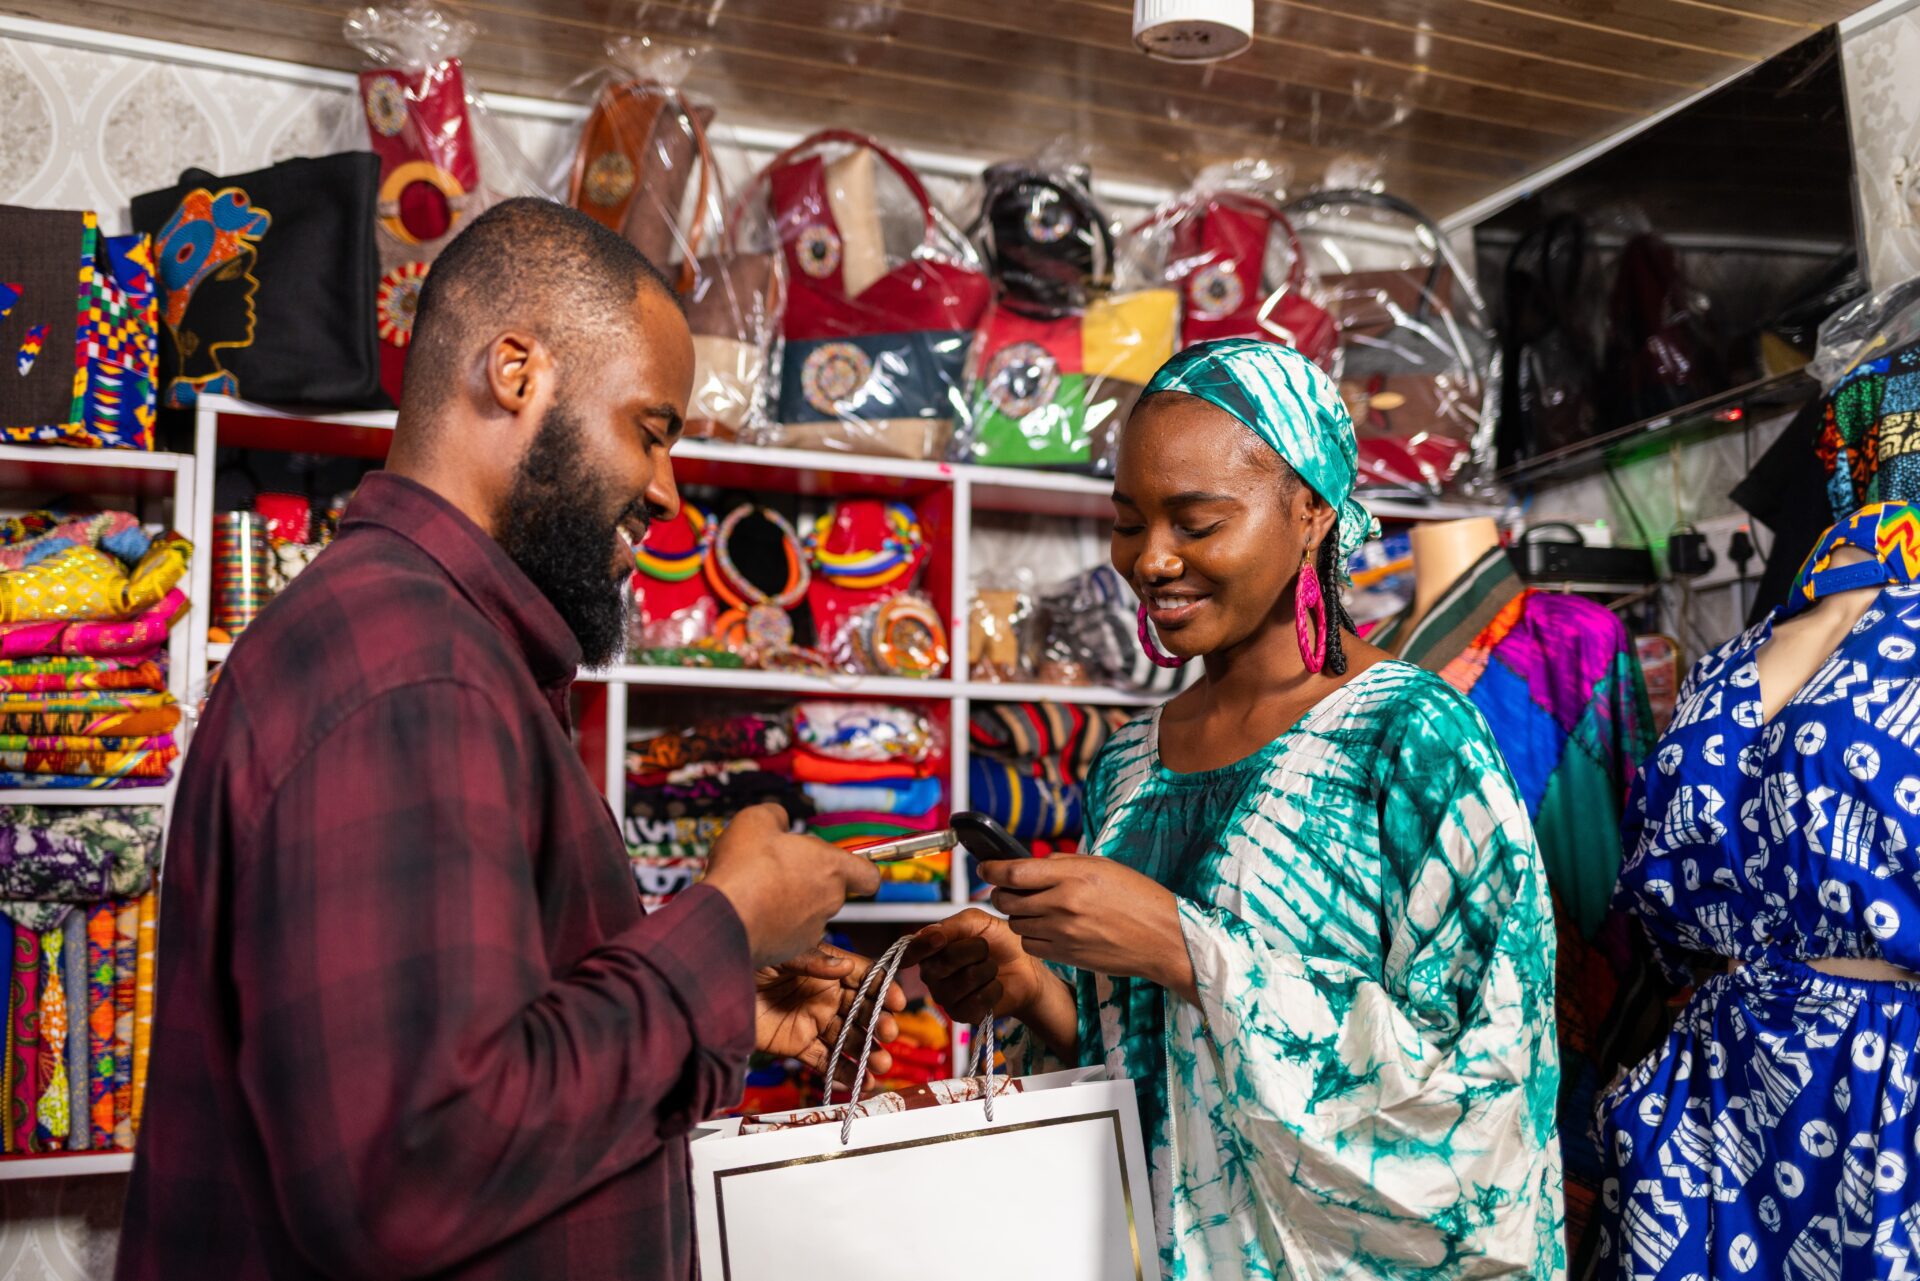
Some merchants are moving fast and already switching from receiving funds into mobile money wallets to bank accounts. Two I interviewed had moved entirely to bank-issued merchant codes. Through eKash, these codes let customers on either mobile network pay directly into the merchant’s bank accounts, with no fee for either side. This fee-free option raises a question: will companies that currently collect merchant payments via MoMo’s P2P rail also start displaying eKash codes at the till? Only time will tell, although one thing is certain for now – eKash allows a wide range of mobile wallets and banks to compete more strongly with MTN’s fee-charging MoMoPay.
To increase adoption, considerable effort went into making the transition into eKash seamless for consumers. For example, MTN and Airtel subscribers already paid merchants through the same USSD string, *182*8*1*[merchant code]#. Since July, that familiar string has worked for any merchant code, whether linked to an MTN or Airtel wallet or to any bank account.
Price still matters but might play in favor of eKash
When MoMoPay’s 0.5% fee returned in 2021, our earlier ICTD study found a significant shift back to cash. For payments within the same network, MTN charges merchants 0.5% for transactions above RWF 4,000 while Airtel applies the same rate for transactions above RWF 5,000. At these thresholds, 0.5% is equivalent to RWF 20 and RWF 25 respectively.
If a merchant payment fee was introduced, a flat RWF 20 fee, charged only above RWF 5,000, would be simpler than a percentage. It never cost merchants more than either wallet and would cost less on larger sales. Both merchants who switched said they could live with a flat fee of RWF 20 per payment, matching the eKash P2P fee cap. Banks could even waive it, recovering the cost through interest on loans.
eKash competition: banks and telcos’ response
Zero-fee merchant payments can shift bargaining power towards merchants by giving them more choice over where their money goes. Telecommunications companies (telcos) have long earned their margins on transaction fees, while banks earn theirs on deposits and lending. Merchants who can route sales into any account for free can choose which provider holds their balances, pushing providers to compete on credit, savings and service.
Providers have responded unevenly. Telcos, initially resistant, now cooperate more. They see little threat in P2P transfers since MTN’s market dominance keeps most transfers on-net while Airtel’s transfers within its network are already free. Banks, in contrast, have resisted more, notably on pricing. Some still steer customers towards the older, fee-paying RTGS route.
Unlike the shared USSD payment process, the way banks offer eKash is not standardised. Some banks route transfers over eKash automatically, with no change to their online banking screens. Others list eKash as a separate option and still let customers choose the costlier RTGS route. This is despite the aforementioned BNR directive which requires interbank transfers below RWF 10 million to be made over eKash. RSwitch says failed transfers fell once BNR began monitoring providers’ service availability and fining them for downtime. Similar scrutiny of how banks present eKash would give customers the same experience at every bank.
Taxing transactions vs. growing the tax base
BNR’s mandate also has implications for tax policy. Should the priority be immediate revenue gains from transaction fees, or wider digital adoption and business growth that could broaden the tax base over time?
By reducing transaction fees, eKash has already eroded the base of a planned 15% excise on financial transaction fees, due to take effect in July 2027. In practice, a 15% fee on a free merchant payment generates no tax, whereas the RWF 20 fee on P2P payments would generate only RWF 3. ICTD research finds that mobile money taxes on much larger fees typically raise only around 1% of tax revenue, while fee levies weigh most on poorer users. The duty therefore deserves a rethink before its implementation, with equity considerations in mind.
The larger fiscal prize, however, is indirect. Takings that once sat in mobile wallets can now land in merchants’ bank accounts, where deposits fund loans and payment histories support cash-flow credit. The bankers’ association already pitches eKash as a platform for data-driven lending. More credit for small firms can mean more output and, in time, a broader tax base.
Merchants’ records will also interest the Rwanda Revenue Authority. In Mexico, where fear of tax keeps many traders relying on cash, the government is promoting a bank account not linked to a tax ID. Rwanda has a parallel in merchant registration: MTN now allows individuals to register for a MoMoPay merchant code from their handsets without providing a tax ID. In fact, our ongoing ICTD study found that 53% of merchants in Kigali had registered for this “informal” merchant code. As fee-free “eKash-to-bank” merchant payments become available, will the government still allow these informal codes? Time will tell.
The larger prize also depends on restraint. If eKash records become a shortcut to heavy-handed enforcement, merchants could retreat to such informal codes or even cash. The shift back to cash in 2021 shows how digital adoption can reverse. If trust holds, wider digital adoption, stronger firms and a broader tax base may ultimately yield more in fiscal receipts than taxing transactions.
What comes next for eKash
Early evidence suggests that digital public infrastructure, priced like a utility, can rebalance a payments market within months. For eKash, three questions remain: can zero-fee merchant payments last? RSwitch is exploring charging acquirers rather than users. How will banks and telcos replace lost fee income? And will merchants who go digital gain credit and grow? For other countries building national switches, the lesson is that interoperability matters—but pricing, provider incentives and the state’s use of transaction data determine whether it delivers lasting benefits for merchants and the wider economy.