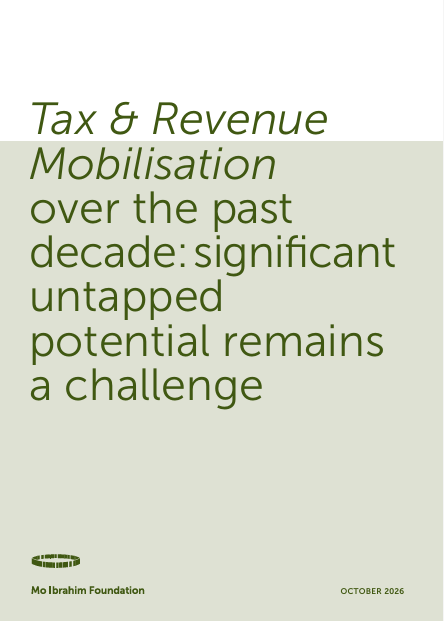
ICTD contributed an analysis to Mo Ibrahim Foundation’s report, titled ‘Tax & Revenue Mobilisation over the past decade: Significant untapped potential remains a challenge’.
Research from the International Centre for Tax and Development (ICTD) shows that sustained revenue gains depend on getting the basics of tax administration right. But strengthening tax administrations requires more than simply increasing staff numbers: it requires bold investment in the skills needed to operate within increasingly digitalised systems, while redeploying skilled staff from routine manual tasks towards higher-value activities such as complex audit cases and direct engagement with taxpayers. Without these investments, digital transformation, automatic exchange of information and wider tax reforms cannot deliver their full potential. Three examples illustrate this.
Firstly, digital public infrastructure (DPI) needs to go hand in hand with investment in administrative capacity. Digital identification, digital payments and secure data exchange can significantly improve the information and processes available to tax administrations. However, the evidence on their impact on revenue and compliance remains mixed: while some countries
have realised important revenue gains, impacts vary across contexts depending on complementary investments in data quality, analytical and enforcement capacity, taxpayer support and appropriate governance. In Senegal, for example, mandatory electronic filing and payment had limited effects on tax compliance. Evidence from Uganda, Ghana, and Rwanda echoes this finding. Technology can therefore strengthen tax administration, but it cannot substitute for the basic capacity needed to use it effectively.
Secondly, getting the basics right also means making better choices about where to direct scarce administrative resources. Too often, governments have doubled down on approaches to tax the informal economy, such as mass registration campaigns and simplified regimes, that raise little or no revenue, while imposing significant compliance costs on low-income operators and contributing to perceptions of unfairness. An alternative, and more promising, approach is to improve the basic functioning of taxes that already exist but that are massively underperforming, such as those on the income of self-employed professionals, property and rental income, and income from investment and capital gains. These offer both revenue potential and greater fiscal fairness. Tax expenditures are another area of reform that can increase both revenue and equity. Better reporting and regular evaluation can help governments identify incentives whose costs outweigh their benefits and replace them with better alternatives.
Finally, international tax reforms show the same importance of strong domestic foundations. New international standards and mechanisms can create opportunities for lower-income countries, but they can only translate into increased revenue if tax administrations have the skills, systems and technology required to implement and use them effectively. Research in seven countries shows that their benefits are uneven and depend strongly on domestic capacity and sequencing.9 International commitments therefore need to be selected and implemented in line with countries’ administrative capabilities.